
How SoLo redesigned its lending marketplace with blind bidding, shifting competition from funding speed to offer quality while keeping the borrower experience simple. The team shares the engineering, reliability, and marketplace design behind the change—and the early results for borrowers.
🕶️ How we redesigned SoLo’s lending marketplace so borrowers could receive more competitive offers, while lenders compete on offer quality instead of reaction speed.
💡TL;DR: We moved from a speed-first funding flow to blind bidding so lenders could compete on offer quality in the background. The early rollout gave us encouraging signals: strong borrower acceptance, hundreds of loans funded during expansion, and reliable conversion of bids into borrower-facing proposals, all while making the borrower experience better.
🔒We’ll focus on the product and engineering patterns behind the redesign, not internal eligibility thresholds, risk models, proprietary decisioning logic.
Marketplaces always end up facing a hard question:
| When multiple people want the same opportunity, who should get it, and why?
For borrowers, that question is not theoretical. It affects the offer they see, the choices they have, and whether the marketplace feels like it is working for them.
For a long time, SoLo’s lending marketplace had a simple answer: a borrower posted a loan request, lenders saw it, and the first lender to fund it got the loan. It was fast, easy to understand, and worked well enough in the earlier days of the marketplace.
But as the marketplace grew, that simplicity started to show its limits. “First come, first served” was no longer just a product flow. It had become an incentive system, and it naturally favored lenders who happened to see and act on requests first.
That created a mismatch. We wanted borrowers to have a better chance at competitive offers. We wanted lenders to have a fairer path to participate. And we wanted the marketplace to become healthier over time, with outcomes shaped more by offer quality than by timing alone.
This was not just a feature build. It was a live marketplace redesign. The team had to change how opportunities were allocated while protecting the things that matter most: borrower trust, system reliability, and a simple product experience.
The team needed to:
This post is about the blind bidding flow, explaining how our team moved SoLo from a speed-first funding model to an offer-based model.
The product goal was straightforward:
| Borrowers should benefit from marketplace competition without having to manage an auction.
Before the blind bidding flow, a borrower could post a loan request and get funded quickly. Speed was valuable, but we saw an opportunity for SoLo to further benefit the borrower. The borrower was setting their terms, and speed was rewarded. We saw an even better path.
With blind bidding, the borrower experience stays simple:
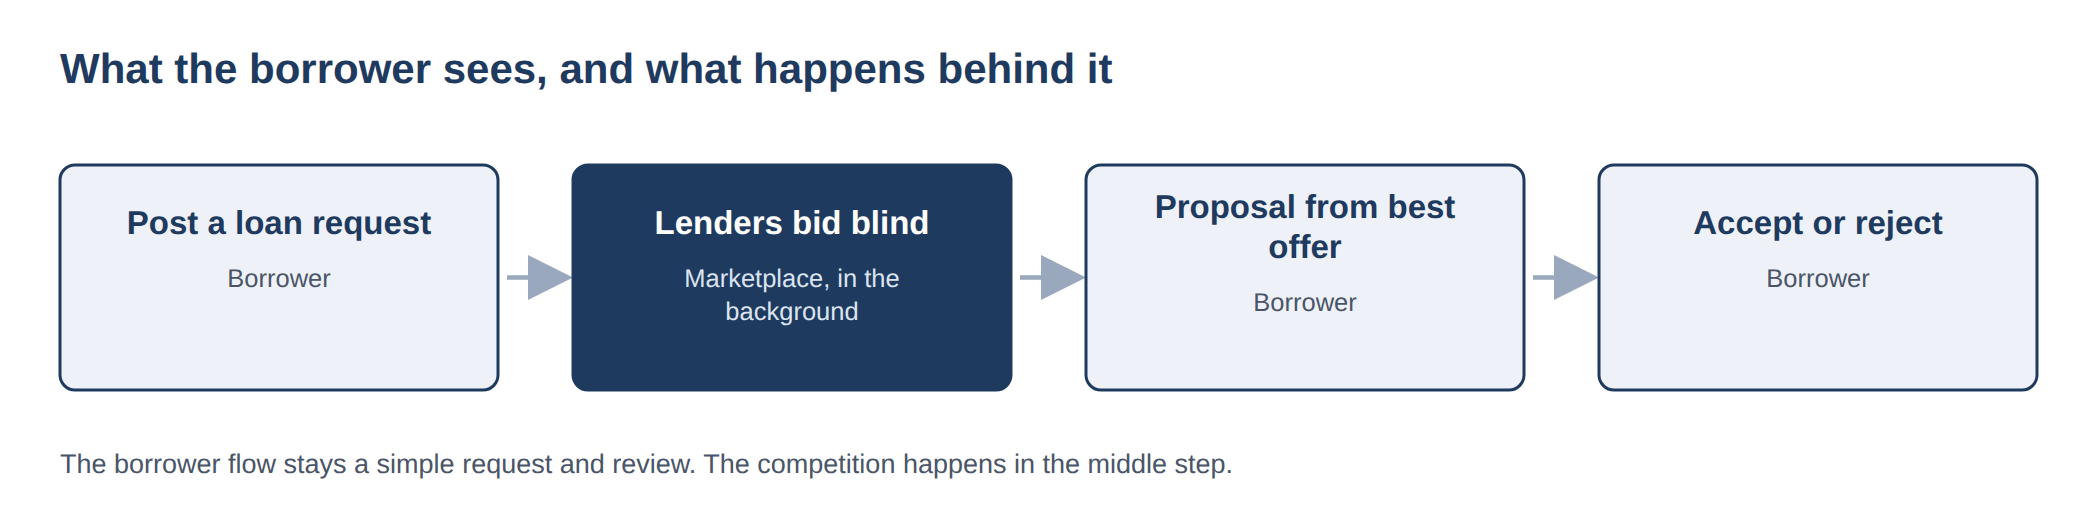
Figure 1: The borrower still experiences a simple request-and-review flow while the marketplace works behind the scenes to surface a stronger offer.
That constraint shaped the engineering work. We could make the marketplace smarter behind the scenes, but we could not make the borrower carry that complexity.
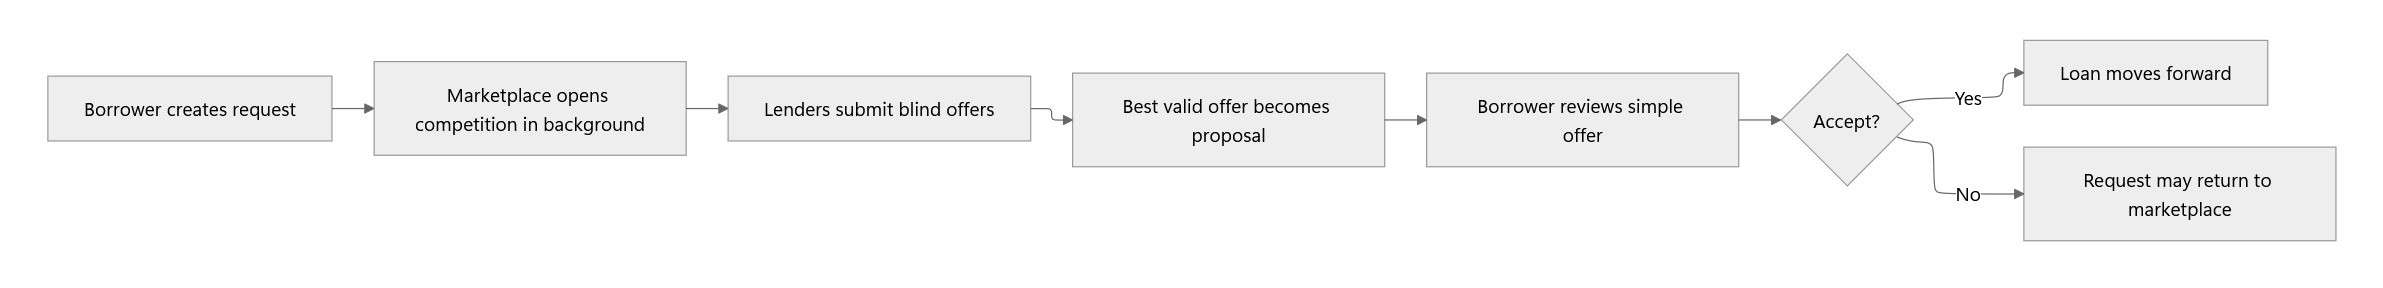
The blind bidding flow adds a short bidding window for eligible loan requests. During that window, lenders can submit offers without seeing competing bids. When the window closes, the system selects the best valid bid and turns it into a proposal for the borrower.
That changes the incentive structure:
The “blind” part matters. If lenders could see every competing bid in real time, the experience could turn into a last-second undercutting game. Blind bidding pushes lenders to make a competitive offer up front instead of reacting to everyone else.
It also helps the borrower experience. When more lenders have a real chance to participate, the marketplace has a better chance to surface stronger offers. The goal was not just to keep loans moving. It was to keep loans moving while making room for better offers to benefit borrowers.
The hard part was not simply accepting bids. The hard part was making every step predictable enough to retry, reconcile, monitor, and explain.
The team modeled the workflow as a state machine:
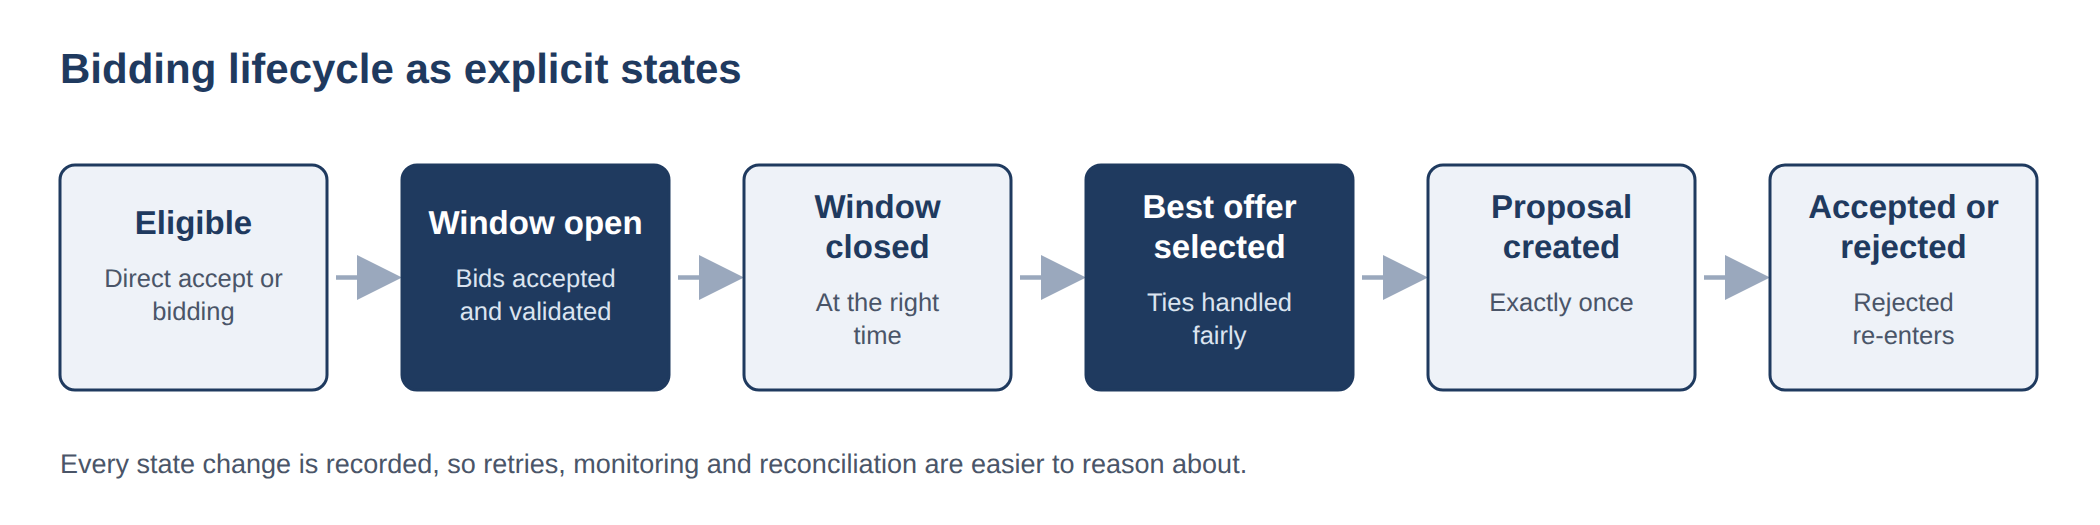
Figure 2: Explicit states made retries, monitoring, and reconciliation easier to reason about.
The workflow needed a clear lifecycle:
1. A request becomes eligible for direct acceptance or bidding.
2. A bidding window opens.
3. Bids are accepted and validated.
4. The window closes at the right time.
5. The best offer is selected fairly.
6. A counterproposal is created exactly once.
7. Rejected proposals follow a defined re-entry path.
8. Every important step is observable and recoverable.
The team also kept the responsibilities separate:
Marketplace rules
Bidding orchestration
Offer selection
Observability
That separation gave us room to move safely. It kept the borrower experience simple while making the backend easier to test, monitor, and improve.
Time-based workflows are easy to describe and hard to run. A bidding window sounds simple: open it, wait, close it. In production, the messy cases matter.
A resolver can restart. A scheduled job can run late. Two workers can try to resolve the same window. A bid can arrive near the boundary. A proposal can be rejected and return to the marketplace.
The team designed for those realities from the beginning. We did not want the system to depend on one perfect timer. We wanted layered reliability:
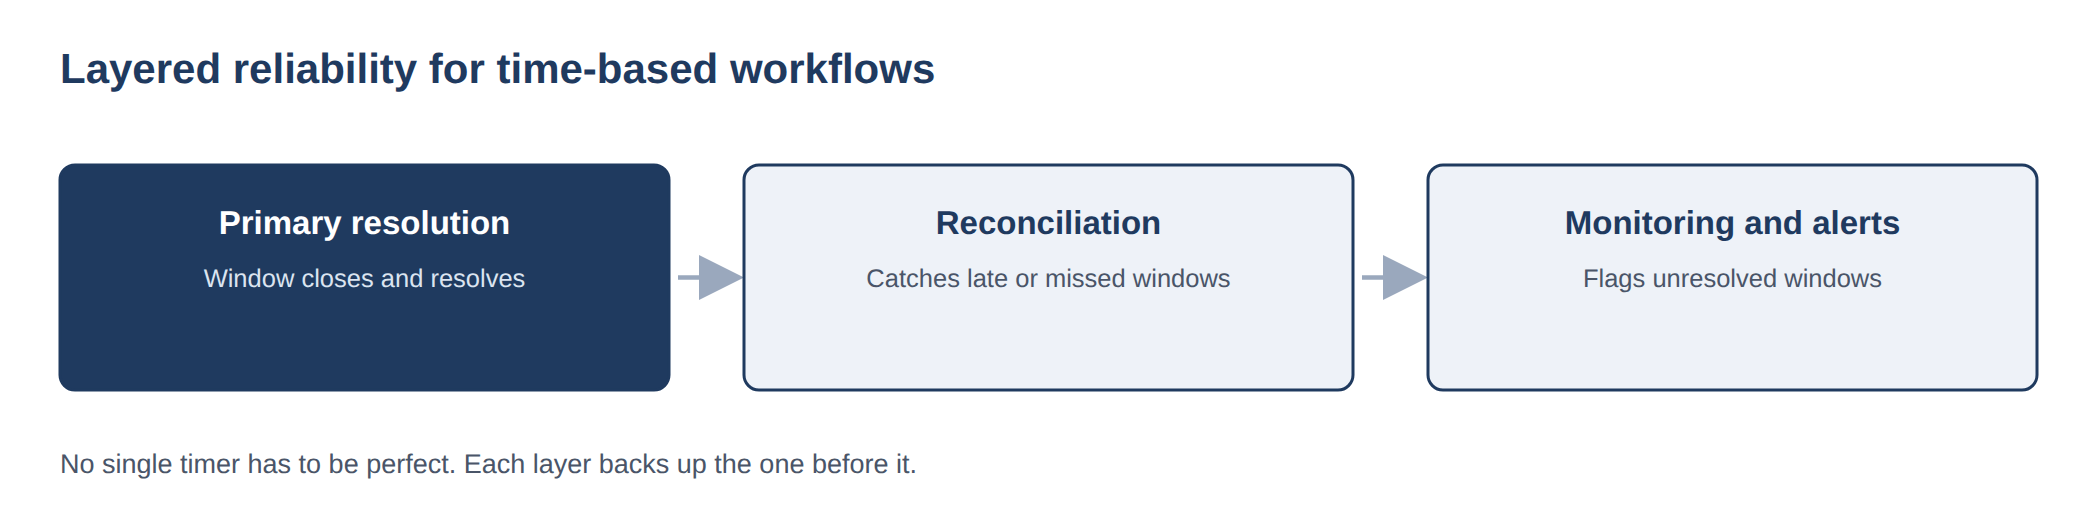
Figure 3: Time-based workflows should include primary resolution, reconciliation, and monitoring paths.
For this kind of workflow, recovery checks need to be part of the original design. They should be:
The lesson for us was simple: if time is part of your product logic, recovery has to be part of the product design.
For borrowers, reliability is part of the experience. A more competitive offer only matters if the proposal appears clearly, consistently, and on time.
Blind bidding can improve price discovery, but it is not enough on its own. A more competitive marketplace also needs guardrails so the same concentration patterns do not simply show up in a new form.
At a pattern level, those guardrails included:
The engineering win was not just introducing a new marketplace rule. It was building the system so fairness-oriented rules could be enforced, observed, and tuned over time.
The blind bidding flow changed how opportunities were allocated, so the team treated rollout more like a controlled migration than a feature toggle.
We started narrow, watched real bidding windows, fixed edge cases, and expanded gradually. The questions we kept asking were:
When a change affects who gets access to opportunities, it affects real consumer outcomes. That makes rollout discipline part of the product experience, not just an engineering best practice.
The team did more than ship a new flow. They changed marketplace behavior with measured risk, operational visibility, and a carefully limited rollout.
The new mechanism produced early rollout signals tied to borrower experience, marketplace health, borrower cost outcomes, and system reliability:
Together, these metrics suggest the new flow was not only helping loans continue moving, but also helping more borrowers receive offers they were willing to accept on more competitive terms.
Those numbers gave us confidence that the system was not just adding a new interaction. It was helping loans continue moving while creating a more competitive allocation model.
The result was a production-ready marketplace capability with measurable borrower impact and operational confidence.
✅ Metrics reflect early rollout signals and are shared to illustrate directionality, not as a guarantee of future marketplace outcomes.
This blind bidding flow is specific to SoLo, but the lessons apply broadly to marketplace engineering.
The blind bidding flow is a good example of the kind of engineering we value at SoLo: product-minded, systems-aware, measurable, operationally disciplined, and grounded in real member outcomes. The team did more than ship a feature. They changed marketplace behavior while keeping the experience simple for borrowers.
That balance of better borrower outcomes, fairer marketplace mechanics, and reliable systems underneath is what made this work meaningful for the team.


