
School is in session. Today, we’re going to talk about one of the most important lessons every SoLo lender needs to master: how to diversify your lending approach so your returns are steady, your risks are balanced, and your participation helps strengthen the entire SoLo marketplace. Whether you’re…

School is in session. Today, we’re going to talk about one of the most important lessons every SoLo lender needs to master: how to diversify your lending approach so your returns are steady, your risks are balanced, and your participation helps strengthen the entire SoLo marketplace.
Whether you’re lending $100 or $100,000, the way you deploy your money , and how often you have to manage it , makes all the difference. That’s where the 3-2-1 Lender Strategy comes in. It’s a tested framework used by top-performing SoLo lenders, and by the time you finish this article, you’ll be able to walk away with a clear playbook for yourself to do more on SoLo Funds.
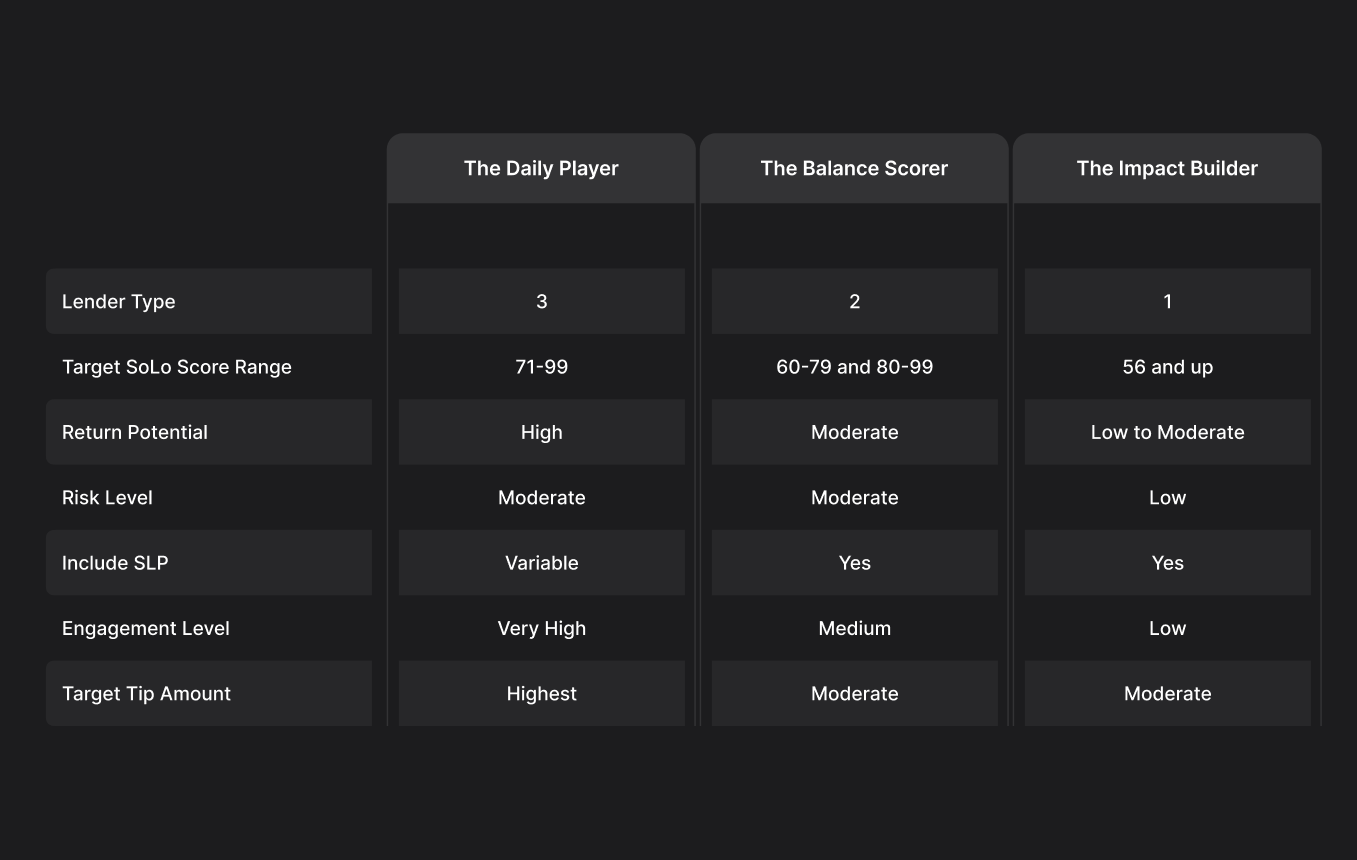
Think of 3-2-1 as three “lending personalities” that help you understand how to do your best on SoLo. These depend on:
This framework is not about locking you into one rigid style , it’s about giving you the language and structure to choose your own strategy. Some people stick to one strategy, while others blend them together into a well-diversified portfolio approach.
In a classroom analogy: the “Daily Player” is like the student who’s deep in the library every night, the “Balance Scorer” shows up consistently to class but without burning out, and the “Impact Builder” is the student who gets good passing grades with steady effort but leaves more time for other things in life.
This is the “all in” strategy , high focus, high capital, best returns.
Portfolio Style: Chasing high-score borrowers with strong repayment histories and high tips.
Traits of a Daily Player:
Tradeoff: It requires a lot of time, attention, and quick reactions. Inventory can be competitive, so you’ll need persistence.
Classroom note: If you’re someone who loves trading stocks in real time or refreshing dashboards, this style may fit your personality. With the launch of SoLo IQ, you might be even more empowered in this method.
Here’s the steady middle ground.
Portfolio Style: A balanced diet of high-score and mid-score loans, mixing tips and protection.
Traits of a Balance Scorer:
Tradeoff: Your returns won’t be as good as a Daily Player, but you’ll sleep easier at night knowing your portfolio is steady and growing.
Classroom note: Think of this as the “honors student” approach , steady, reliable, doesn’t need the spotlight, but always delivers.
For those who want to engage, make an impact without the stress.
Portfolio Style: Lots of smaller bets across a wide pool of borrowers, at least 20 per month.
Traits of an Impact Builder:
Tradeoff: Returns are more modest, but this approach is highly accessible and low-stress, especially for newer lenders.
Classroom note: This is like the student who takes the core classes seriously, but also has room for hobbies, sports, or family life. It’s not flashy, but it’s sustainable and it gets the job done.
Think of these as your classroom “study hacks”:
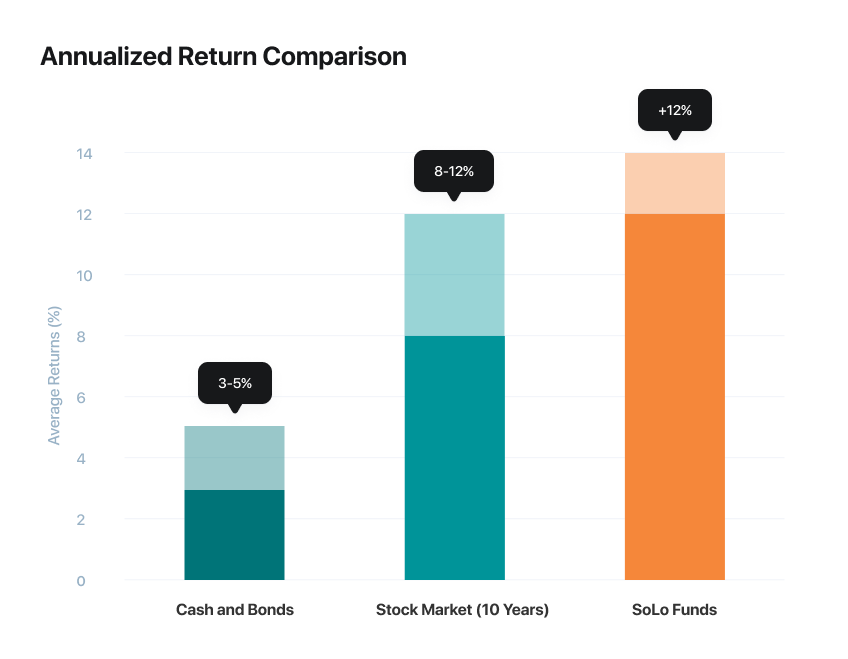
Here’s how SoLo stacks up:
InstrumentAnnualized ReturnsCash & Bonds3–5%Stock Market (10 yr)8–12%SoLo Funds+12%% via diversified lending average in 2023
Example: A diversified $1,000 portfolio across 20 loans could generate ~$120 in monthly returns , far exceeding CDs or savings accounts.
Classroom note: You’ve essentially built a high-yield mini-portfolio on your phone.
SoLo isn’t just peer-to-peer lending anymore , it’s part of Wealth Tech.
That’s what makes SoLo unique , you’re not just lending; you’re participating in a new asset class.
The 3-2-1 Lender Strategy is more than a framework , it’s a market-tested playbook for building wealth on SoLo Funds.
And remember: the best lenders aren’t just making money; they’re helping real people access opportunity, which in turn breeds even more opportunity for lenders. That’s the future of Wealth Tech , and SoLo is where it starts.
Want to dig deeper into fees, risks, and SoLo’s unique difference? Read:


